Today's menu
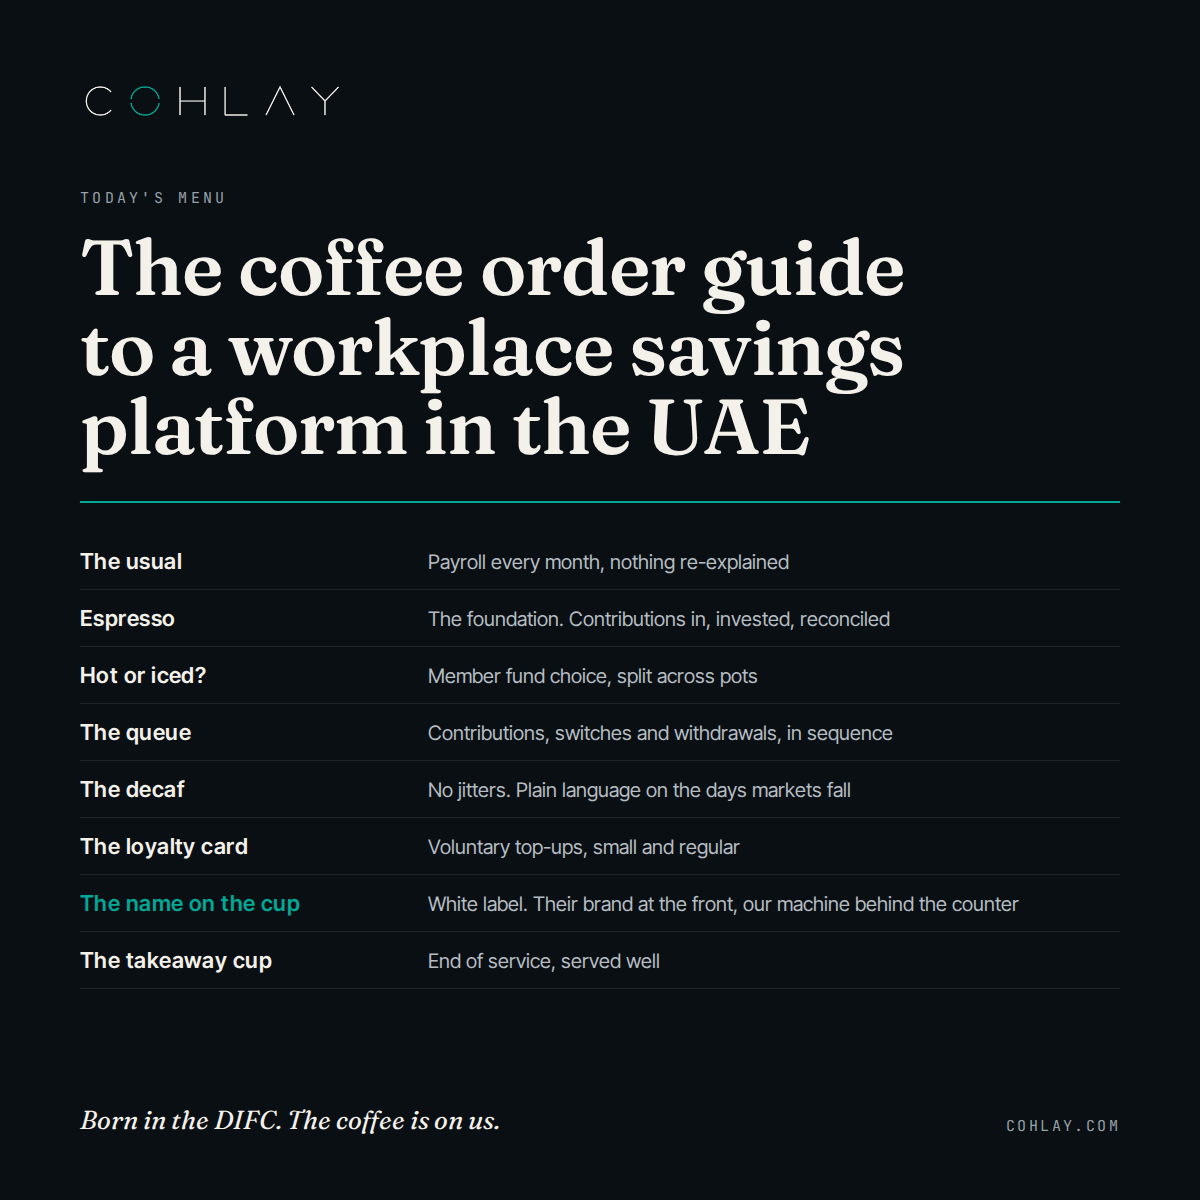
The coffee order guide to a workplace savings platform in the UAE
Published 22 September 2026 · 7 min read
Most problems in workplace savings are order problems. Someone asked for one thing, the system made another, and nobody noticed until the cup was already on the counter.
We notice this because of where we work. We were born in the DIFC, a district where you are rarely more than a minute's walk from a latte, and where a fair share of the region's financial decisions get made in the queue for one. Spend enough mornings there and you start to admire the operation behind the counter. Hundreds of orders, each slightly different, all made correctly, in sequence, with the till balancing at close.
That is a fair description of what a workplace savings platform in the UAE has to do with gratuity and end-of-service benefits. So here is the menu.
In plain terms: a workplace savings platform is the technology that runs the monthly operational cycle behind a workplace savings or end-of-service benefits scheme. It processes employer contributions, reconciles cash against contribution files, prices fund units, executes trades, maintains member portfolios, handles withdrawals and produces reporting — every month, for every enrolled employee.
For a fuller definition, see What is a workplace savings platform?.
First, what is being ordered: end-of-service benefits in the UAE
For most private sector employers, end-of-service benefits in the UAE still mean gratuity: a lump sum based on basic salary and length of service, paid when employment ends.
There is now a voluntary alternative. Under the alternative end-of-service benefits scheme, employers who opt in make monthly contributions into approved investment funds for the employees they enrol, and gratuity accrued before enrolment is preserved. People sometimes call it a workplace pension for the UAE. It is closer to an employee savings scheme: money set aside every month, invested, and building up in the member's name.
That changes the job. Managing employee gratuity used to mean a spreadsheet and a provision in the accounts, settled once at the end. A funded scheme is an operation you run every payroll cycle, for every enrolled employee, for as long as they work for you.
Which brings us to the counter.
'I'll have the usual': payroll, every month, without re-explaining
Regulars do not recite their order. The barista already knows it, and that is most of the reason they come back.
A good employer gratuity platform treats the HR team the same way. Templates are configured once and carried into every cycle. Changes are communicated to participating employers clearly and in advance. When a file is uploaded, the platform flags what is wrong with it row by row, before submission, instead of three days after. The aim is for the monthly run to be uneventful.
The espresso: contributions in, invested, reconciled
No milk, no syrup, nowhere to hide. Espresso is the test of a cafe because everything else on the menu is built on it.
The platform equivalent is the core contribution cycle, and it starts with a clear division of labour. The employer works out what is owed: 5.83 per cent of basic salary for employees with under five years of service, 8.33 per cent from five years onwards. That calculation, and the salary and service records behind it, sit with the employer.
Our job is to make it exactly as ordered. The payroll file is checked in full before anything moves, with every row matched to a member and every amount accounted for against the money received. Contributions are split across each member's chosen funds, trades are batched, and the bank account is reconciled against the ledger.
This is the part of gratuity administration software that nobody demos, and the part that matters most.
Hot or iced? Member choice
The funds on the menu come from the licensed fund manager of the scheme. Members choose between them, split contributions across more than one pot, and can change their strategy over time. A platform has to treat that as normal, with each member holding their own mix and switching when they choose, while the queue behind them keeps moving.
The queue: orders made in the order they were placed
Anyone who has stood in a DIFC cafe at 8.15am knows sequence is everything. A contribution, a fund switch and a withdrawal can all land on the same account in the same week. They have to be processed in the right order, at the right prices.
With a few hundred members you can fix this by hand. With tens of thousands you cannot, and that is the line between enterprise workplace savings software and a portal with a login page.
The decaf: for the days the market gives you the jitters
Markets fall. Members log in, see a smaller number than last month, and reach for the nearest button. What helps at that moment is context in plain language: what has happened, what long-term saving looks like, and what the choice in front of them means.
This is where a digital gratuity platform earns the word digital. It is information, not advice, delivered at the point of decision.
The loyalty card: small, regular, and it adds up
Nine stamps and the tenth is free. The mechanics are trivial, and they work because they make a habit visible.
Employees can make voluntary contributions on top of what their employer pays in. Savings streaks, payday prompts, goal setting and a clear view of the future balance are what turn an end-of-service entitlement into an employee savings scheme people actually use.
The name on the cup: the white-label gratuity platform
The customer's relationship is with the name on the cup. They never think about the grinder, the machine, or whoever serviced it at 6am, and that is how it should be.
For a fund manager moving into workplace savings in the UAE, or a bank extending its investment range to employers, a white-label investment platform works the same way. Their funds, their brand and their client relationships sit at the front. The workplace savings fund platform underneath, the portals and the administration, runs behind the counter. This is the part Cohlay builds: the machine, not the logo on the cup.
The takeaway cup: when someone leaves
End of service is the moment the whole scheme exists for. What a member takes with them is their accumulated contributions and the investment returns on them. The questions are simple. What belongs to this person, what is it worth today, and how easily can it be settled? The answers should take minutes, and the digital experience is what will be remembered.
Closing the till
At the end of the day, every cup sold has to match the money in the drawer. For a workplace savings platform that means reconciliation, a full audit trail, and records that an employer, a fund manager or an auditor can each read without calling someone to explain them.
Cohlay is modern gratuity infrastructure, born in the DIFC and built for the fund managers and administrators behind workplace savings in the UAE, with the wider GCC in mind. If you are in the district, the coffee is on us. Contact us at admin@cohlay.com.